How Much House Can I Afford? The Real Monthly Payment (PITI)
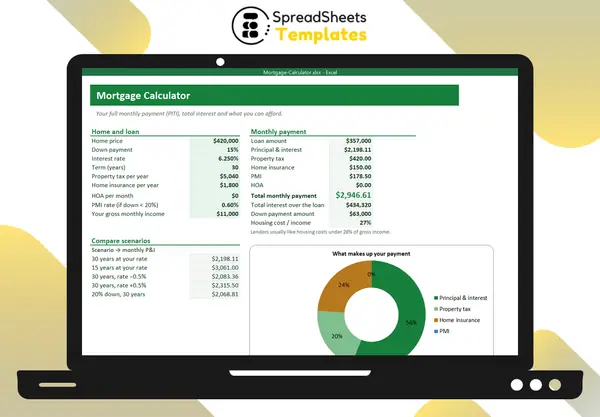
The question isn’t “how big a loan will the bank give me?” — it’s “what monthly payment can I live with?”. To answer it you need the full payment, known as PITI: principal, interest, taxes and insurance (plus PMI and HOA if they apply).
The parts of a mortgage payment
- Principal and interest (P&I): the loan payment itself. In Excel:
=PMT(rate/12, years*12, -loan). - Property tax: yearly tax ÷ 12.
- Homeowners insurance: yearly premium ÷ 12.
- PMI: private mortgage insurance, usually required when the down payment is under 20%. Often 0.3–1.5% of the loan per year.
- HOA dues: if the home is in an association.
Example
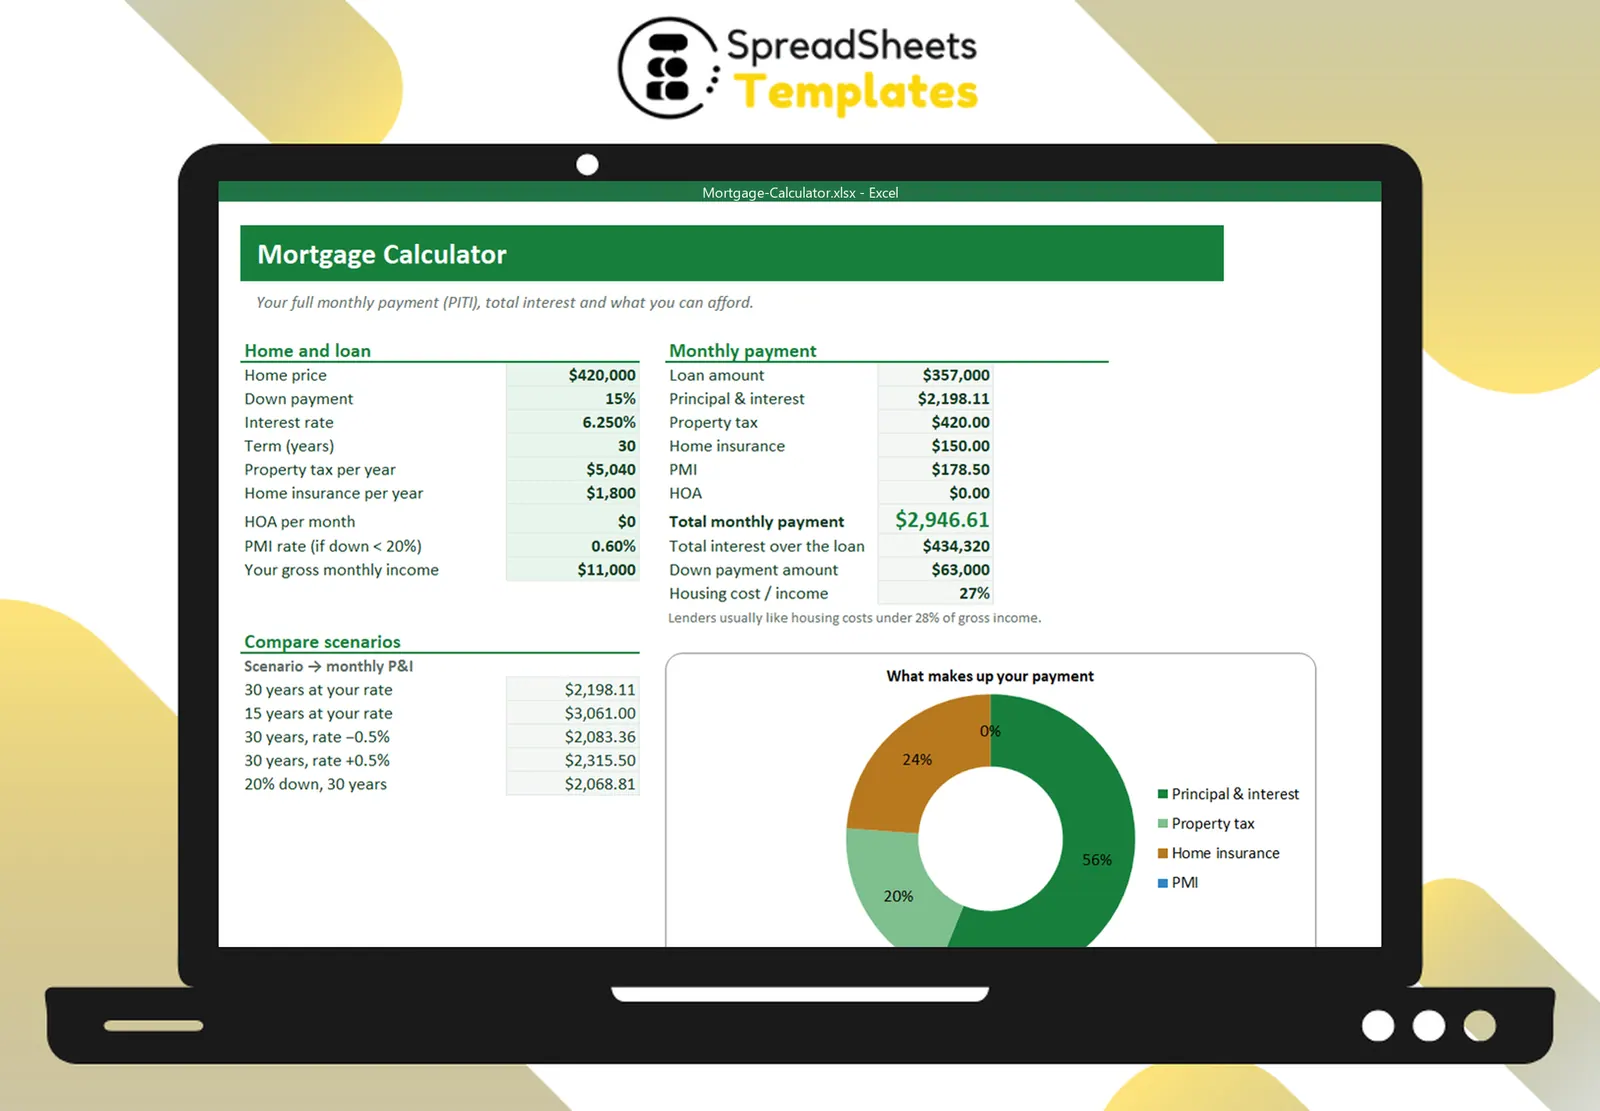
A $420,000 home with 15% down at 6.25% for 30 years:
| Item | Monthly |
|---|---|
| Principal & interest | $2,198 |
| Property tax ($5,040/yr) | $420 |
| Insurance ($1,800/yr) | $150 |
| PMI (0.6%) | $179 |
| Total | $2,947 |
P&I alone would suggest about $2,200 — the real payment is almost $750 more.
The 28% guideline
Many lenders like housing costs (PITI) under 28% of gross monthly income, and total debt payments under 36–43%. With an $11,000 gross monthly income, $2,947 is about 27% — on the edge. It’s a guideline: your comfort also depends on other debts, savings and job stability.
15 vs 30 years
A 15-year loan has a higher payment but far less interest. In the example, P&I goes from about $2,200 to $3,060 a month, but total interest drops dramatically. A middle path: take the 30-year loan and make extra principal payments when you can.
Small rate changes, big differences
Half a percentage point changes the payment by roughly $110 a month on this loan — over $40,000 over 30 years. It pays to shop lenders and improve your credit score before applying.
Don’t forget
- Closing costs (2–5% of the price) are paid upfront.
- Maintenance: budget around 1% of the home’s value per year.
- PMI can usually be removed when you reach 20% equity.
Template
The Mortgage Calculator gives you the full monthly payment with taxes, insurance, PMI and HOA, total interest, the housing-cost-to-income check, five scenarios side by side and a by-year table of balance and equity. For every individual payment and extra-payment savings, use the Loan Amortization Schedule.